Traditional Banks or Fintechs: Where Credit is Cheaper
Credit options play a crucial role in the financial lives of Australians, with traditional banks and fintech lenders offering distinct advantages.
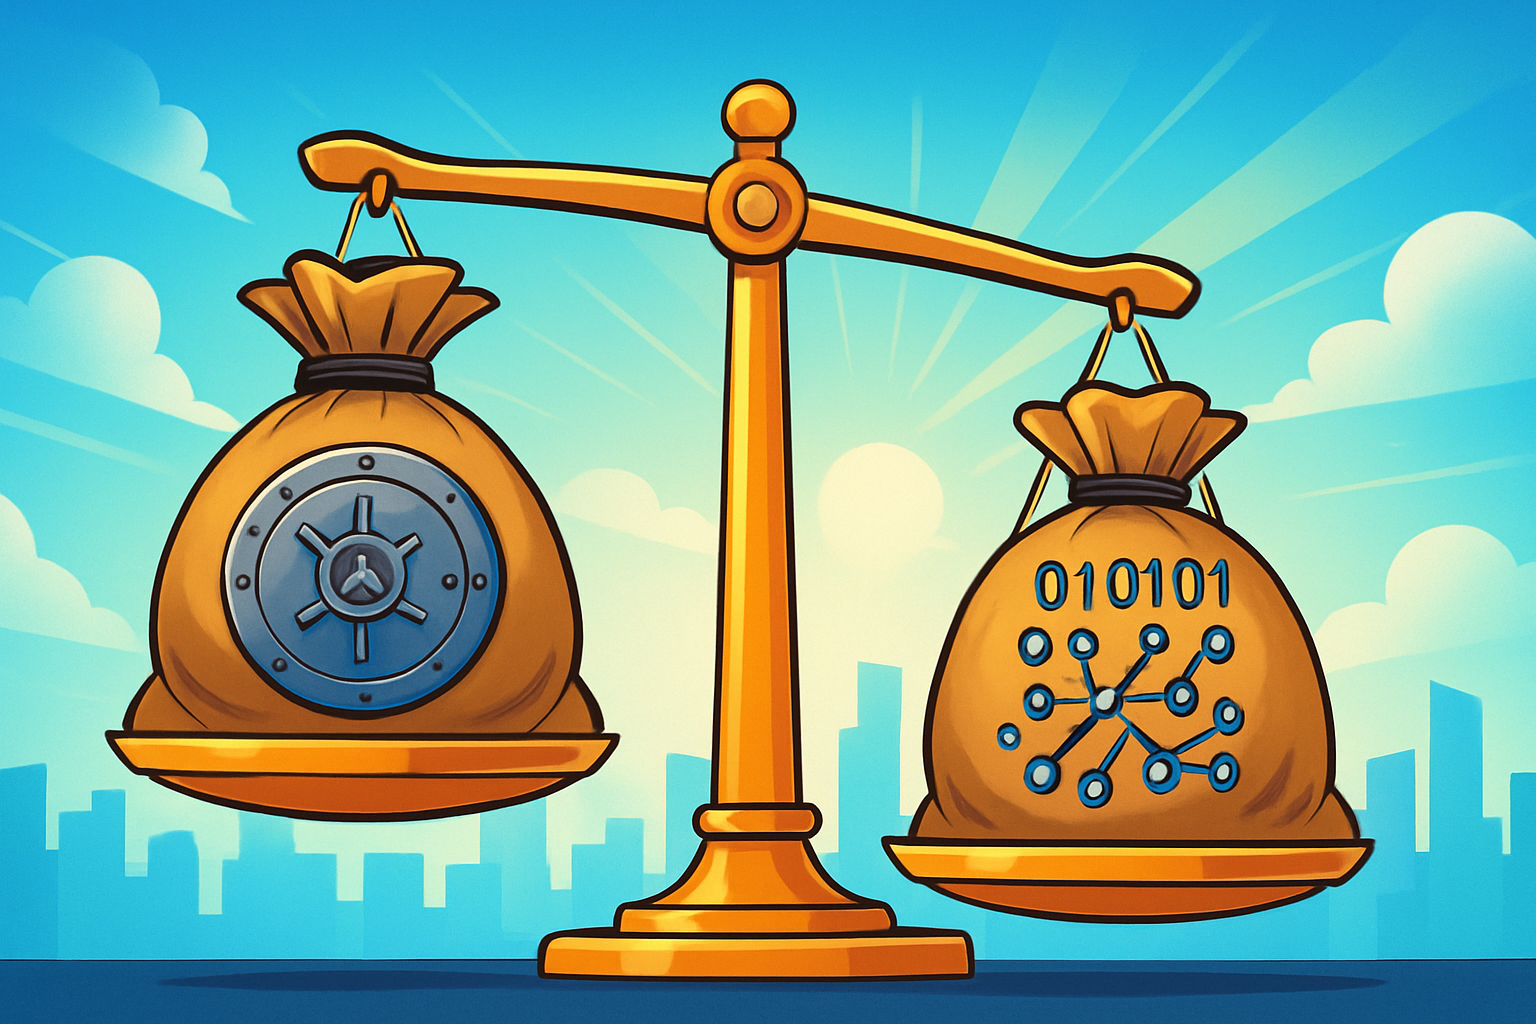
This article will explore the cost benefits of traditional banks, the low overhead of fintech lenders, and how their differing approaches to loan rates and services impact consumers.
Discover how to apply for flexible personal loans up to AUD 50,000
Understand how to claim Wallet Wizard loans up to AUD 8,000
See how to unlock Cash Converters loans up to AUD 5,000
As the financial landscape evolves, understanding these dynamics can help individuals make informed decisions about where to seek credit, whether they prioritize lower rates, comprehensive services, or innovative lending solutions.
Australia’s Credit Landscape Today
In Australia’s dynamic credit scene, the evolution from traditional lending models to digital platforms marks a significant shift.
The rise of digital lenders is aggressively reshaping how Australians perceive borrowing options, compelling traditional banks to reevaluate their operational strategies and models.
Meanwhile, fintech lenders actively leverage technology to streamline processes, offering competitive rates that disrupt conventional lending norms.
This transformation impacts credit costs, directly influencing household budgets and business expansion decisions.
As fintech entities operate with minimal overheads, they provide appealing lower rates compared to the historically cheaper credit offered by traditional banks with access to low-cost funding.
However, traditional banks still hold an edge with their comprehensive service offerings, noted in resources like the Major Australian banks analysis, underscoring their stable performance.
Exploring these aspects in-depth will provide valuable insights into the evolving lending rate structures and their implications on borrowers in Australia today.
Operational Costs Driving Bank Loan Prices
Australian traditional banks in 2024 face significant operational and regulatory costs, impacting their loan pricing strategies.

These expenses arise from several key areas that demand continuous financial attention, all of which influence their interest rate structures.
- Branch network upkeep
- Technological investments
- Compliance with regulations
- Labor costs
Each of these categories contributes directly to the cost structure of banks.
For example, maintaining a robust network of branches ensures customer accessibility but incurs substantial real estate and staffing expenses.
Similarly, investing in technology is essential to provide competitive services and secure communications, as evidenced in the KPMG Analysis on Bank Costs.
Compliance with capital adequacy regulations not only requires capital reserves but also involves intricate reporting processes, demanding specialized staff training.
These operational demands lead banks to adjust their loan interest rates upward, reflecting the need to cover these comprehensive expenses.
Fintech Efficiency and Pricing Power
Fintech lenders in Australia have strategically utilized digital platforms to streamline their operations, allowing them to offer competitively priced loans against traditional banks.
By leveraging technology and cutting out middlemen, these fintech firms reduce operational expenses significantly.
This efficiency not only streamlines processes but also translates into more affordable credit options for consumers.
- Automation cuts processing costs: Fintech companies automate loan underwriting and processing, eliminating the need for extensive manual intervention.
- Reduced overhead through digital-only presence: Operating without physical branches cuts down on real estate and utility expenses.
- Data-driven decision making: Using data analytics, fintechs quickly assess creditworthiness, which speeds up approvals reducing associated labor costs.
- Scalable digital solutions: They offer scalable platforms that grow with demand, avoiding costly infrastructure expansions.
These agile and technology-enabled structures empower fintechs to price loans more attractively.
This pricing advantage, illustrated by lower interest rates, has allowed fintech companies to successfully capture market share from traditional banks.
For insights into how this fintech efficiency impacts the financial landscape, see The Australian Fintech Landscape.
Average Interest Rates in 2024
The financial landscape in Australia continues to evolve as both traditional banks and emerging fintech companies compete to offer competitive loan products.
This shift creates a diverse range of options for consumers seeking personal loans, mortgages, and business financing.
| Loan Type | Traditional Bank Average Rate | Fintech Lender Average Rate |
|---|---|---|
| Personal Loan | Bank 9.2% | Fintech 7.8% |
| Mortgage | Bank 5.49% | Fintech 4.79% |
| Business Loan | Bank 8.44% | Fintech 7.25% |
Analyzing the data, fintech lenders consistently offer lower interest rates across various loan types, making them a compelling choice for borrowers who prioritize cost-effectiveness.
In particular, the most striking contrast appears in mortgage rates, where fintechs provide a significant advantage.
You can explore these options more deeply through platforms like Mortgage Choice, which allows consumers to compare offerings and potentially save on financial expenditures.
Beyond Price: Services that Matter
Traditional banks like the Big Four in Australia robustly equip their customers with extensive financial services while maintaining an impressive network of branches across the nation.
Customers enjoy relationship managers who provide personalized advisory support, helping clients navigate complex financial situations.
In contrast, fintech lenders focus on leveraging technology to offer 24/7 app-based assistance, utilizing advanced mobile banking apps that streamline customer experiences.
As pointed out by KPMG’s insights, fintechs excel in efficiency and convenience while making strides in digital lending.
However, traditional banks’ extensive network reach remains a relevant strength, offering face-to-face interactions that cater best to those who prefer in-person services.
Meanwhile, Forrester’s analysis highlights advancements in mobile applications from these giants, integrating innovative tools.
These features bridge the gap between traditional services and fintech efficiencies, offering consumers a hybrid approach in managing their financial needs.
Deciding Who Offers Cheaper Credit
Understanding who offers cheaper credit between traditional banks like the Big Four and fintech lenders in Australia involves various factors.

Traditional banks often provide lower loans due to their access to low-cost funding (Big Four Banks Credit Advantage), but this option generally requires a strong credit score and extensive documentation (Bank Loan Requirements).
This often limits access to those with established credit histories, which traditional banks consider crucial in assessing risk.
By contrast, fintech lenders have disrupted the market by minimizing overheads, allowing them to offer competitive rates with streamlined applications (Fintech Advantages). \n\nFintechs emphasize speed and flexibility, tailoring services to Relevant text for small business and personal loans when immediate funding is necessary, and traditional criteria are not met (Fintech Flexibility).
If your need is for fast approval and you’re comfortable with slightly higher rates, fintechs might suit your needs better.
However, when considering a long-term relationship and multiple banking services, traditional banks might be the better option. \n\nAdditionally, knowing your loan purpose can guide your choice.
Whether the need is for a secured,long-term loan (Traditional Banks for Secured Loans) or a short-term working capital infusion, understanding these elements will aid in selecting the most cost-effective option.
It’s crucial to evaluate both current and future needs since both traditional and fintech options provide unique benefits depending on the circumstances.
Consider the total cost of credit including fees and service quality to find the most advantageous solution for your financial scenario (Fintech Service Quality).
In conclusion, both traditional banks and fintech lenders present unique credit options that cater to varying financial needs.
By weighing these differences, borrowers can choose the lender that best aligns with their specific requirements.