What To Do If Your Card Is Declined
Card Decline can be a frustrating experience for anyone trying to make a purchase.
Understanding the steps to take when your card is declined is essential for resolving the issue quickly.
uncover-the-advantages-of-your-rewards-credit-card
credit-card-rewards-earning-rates-and-eligibility-overview
is-the-no-foreign-transaction-fee-card-really-worth-it
In this article, we will explore the various actions you can take, starting from verifying your card information, attempting the transaction again, and ultimately reaching out to your card issuer’s customer service.
By knowing how to navigate these challenges, you can minimize disruptions and ensure a smooth transaction process in the future.
Immediate Steps After Your Card Is Declined
Experiencing a card declined moment can indeed be stressful, but remember, it’s a common hiccup that can be handled smoothly.
Start by focusing on a simple three-step action plan to get back on track.
First, verify information: double-check your card details like the number, expiration date, and security code to ensure everything is entered correctly.
Even a small error can lead to a decline, so this step is essential.
Once you’ve confirmed everything is correct, try running the transaction again.
Sometimes, it could be just a glitch in the system.
Retrying can often resolve a minor issue and put your purchase through without further fuss.
If you’re looking for more advice on how to handle these situations, Nerdwallet’s insights might be useful.
If your card still doesn’t work, it’s time to reach out to customer service.
Use the number on the back of your card to contact your card issuer.
They can provide the specifics about why your card was declined and help you resolve any issues like a spending freeze or exceeding your available credit.
- Check details
- Retry calmly
- Call the issuer
Verify Your Card Information
In the realm of online transactions, verifying your card information becomes crucial when facing a decline.
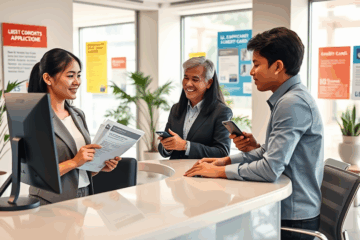
Double-checking your entries is an essential first step.
Focusing on precision with your card number, expiration date, CVV, and billing address can prevent frustrating declines.
Each field serves a critical role: the card number identifies your account, the expiration date ensures the card’s current validity, and the CVV adds a layer of security.
An error as small as a mistyped CVV, like 123, can lead to an immediate decline, disrupting your transaction process.
Refer to resources like the Primer Guide on Soft Declines for further insight into managing these issues.
Even seemingly minor details, like a stray digit or misspelling in the billing address, may trigger a denial.
Such incorrect information can prevent successful payment processing.
Spotting these errors is pivotal for ensuring smooth and hassle-free online transactions, and can often resolve the issue without additional support.
Retry the Transaction Smartly
When a payment declines, adopting a calm and methodical approach to retrying the transaction can make all the difference.
First, it’s important to wait a minute before attempting the payment again.
This pause helps prevent unnecessary security flags from being triggered due to rapidly repeated attempts, which can be seen as suspicious by fraud detection systems.
While waiting, double-check to confirm your internet connection; a stable connection ensures that your transaction processes smoothly when you retry.
As you proceed, ensure that you have entered all payment details accurately to prevent duplicate charges and further frustrations.
Using insights from service providers such as AppFrontier, businesses can implement effective retry strategies that optimize payment success rates.
Additionally, the advice from platforms like PayPal suggests timing retries based on specific decline reasons, making informed decisions essential in alleviating decline issues.
Contact Your Card Issuer’s Customer Service
When your card gets declined, a direct approach to resolving the issue is reaching out to your card’s issuer using the number found on the back of the card.
This proactive step allows you to address the problem quickly by speaking to customer support.
When connected with them, ask pertinent questions regarding any possible holds, fraud alerts, or your current account status.
According to a banking specialist, “Your fastest route to resolution is a proactive call.”
Prepare before calling by having the following information ready:
- Full card number
- Most recent transactions
- Photo ID
These details help the issuer verify your identity and provide faster assistance.
Once the issue is identified—whether due to a security hold or exceeding your credit limit—confirm that the problem has been resolved during the call.
Additionally, inquire about any necessary steps you should take before attempting the transaction again.
It’s important to follow up after your customer support call to ensure that the transaction can be retried without issues.
Often, resolving a declined card transaction is simply a matter of clarifying misunderstandings with your issuer, allowing you to proceed with confidence.
Identify and Fix Underlying Decline Causes
Identifying and fixing the underlying causes of card declines is crucial for ensuring seamless transactions.
Before taking corrective action, it’s essential to recognize whether the issue stems from insufficient funds, credit limits, fraud holds, or expiration dates.
Understanding these factors can save time and frustration while allowing for a more efficient resolution.
Common Decline Reasons and Quick Fixes
Encountering a declined transaction can be frustrating.
However, understanding the common triggers behind these declines can help you tackle the issue quickly.
Common decline reasons often relate to issues such as insufficient funds, an expired card, or fraud protection.
For example, ensuring there is enough balance on the card or checking the expiration date can prevent common mishaps.
In other instances, communicating with your issuer could swiftly resolve holds placed for security.
To give you a better view of typical causes and solutions, here’s a helpful table:
| Reason | Self-Help Action |
|---|---|
| Insufficient funds | Add money or choose another card |
| Expired card | Request a renewed card from your bank |
| Fraud protection | Contact your issuer using the customer service number |
| Maxed-out limit | Pay down your balance or request a limit increase |
By taking these actions promptly, you can ensure smoother future transactions.
Resolve Credit Limit or Hold Problems
Encountering a declined credit card due to credit limits or holds can be frustrating.
However, understanding the steps to resolve these issues is crucial.
Start by examining your available credit, which helps identify whether you are nearing your credit limit.
You should contact your card issuer to request a temporary limit increase if needed.
Simultaneously, ensure there are no pending large transactions causing holds by consulting with the merchant.
Next, verify any suspicious activities as card issuers often place holds to prevent fraud.
As highlighted in a Capital One guide, it’s essential to stay vigilant: “Security always prioritizes customer protection.
” If fraud or unusual activities are detected, promptly report them and provide any necessary documentation to the issuer.
Additionally, you may need to offer proof of identity or recent spending records to rectify holds.
Always remain in contact with your card issuer for updated information, ensuring all steps are taken to lift any credit-limit or security holds swiftly and efficiently.
Card Decline can happen to anyone, but knowing how to respond effectively can ease the frustration.
By following the outlined steps, you can quickly resolve issues and get back to making your purchases with confidence.